
The second quarter earnings calls of the Permian Basin land and water companies were filled with interesting announcements and collectively were as bullish as I have seen in a while. I think it is worth discussing some of the interesting announcements, particularly as they pertain to datacenters and the produced water / solid waste narrative that I often write about. Before we dive into the Permian Basin, let’s start with a little trash talk coming out of Canada, as some of it relates to the companies in the Permian.
Secure Waste Infrastructure Corp. and GFL Environmental
As I previously wrote about (1), GFL announced in April its intention to acquire Secure – thanks GFL for helping to prove out my produced water / solid waste thesis! The transaction is under review by Canada’s Competition Bureau, although no one believes this to be an issue. GFL has even raised the debt it needs to close the transaction in advance of the Bureau’s ruling. Subsequent to the Secure Transaction announcement, it has been reported GFL has been approached by several sponsors who are interested in taking GFL private. Let’s take a look at both companies’ earnings releases and their ramifications.
Starting with Secure, its results were fantastic. Secure’s revenue was up 19% and its per share EBITDA was up 20%. Furthermore, future growth is foreshadowed in management’s expectation to deploy $100MM of growth capex this year.
GFL also had strong results, delivering a 14.8% increase in EBITDA. Management expects to end the year delivering over 15% growth in EBITDA and over 20% growth in FCF; this is without any contribution from Secure. Management noted that if the Secure transaction were to close in Q4, then EBITDA growth could be greater than 20%.
There was a lot of disclosure around the potential take private of GFL. Here is what stood out to me:
Management feels vindicated as significant unsolicited interest from private equity shows that there is a dislocation between GFL’s share price and intrinsic value.
CEO Patrick Dovigi is quite bullish on GFL, stating “I’m not a seller at $40 [USD]. I am not a seller at $50. I’m not a seller at $60. I’m not a seller at $70, and I’d be rolling 100% of my equity into whatever is sort of being proposed. I think there’s a lot of opportunity here.”
Patrick also stated “…that some of the smartest and largest institutions in the world have the biggest pockets of capital believe this company is undervalued and can generate mid-teens to 20% IRRs, even paying a premium to where the stock is trading today”. This is significant for a couple reasons. First, in the event a take private does not happen, GFL shareholders can still look forward to strong returns in the future. Second, the IRRs levels that are being contemplated seem to indicate that GFL may end up in a core fund, which is similar to what happened with GFL’s ES business. If it is true, sponsors view GFL as a lower risk asset. They would also not likely lever it up excessively, which would make executing an LBO easier, as it is less reliant on raising debt capital. The later point was bolstered by Patrick stating that the debt investors aren’t concerned about a buyout leading to traditional LBO levels of debt such as 6-plus turns of leverage. He added that leverage amount isn’t really being proposed, not that the business couldn’t handle it.
If the call wasn’t bullish enough, Patrick stated “…started [GFL] over 20 years ago now. I don’t think I have a better opportunity than anything I see to continue compounding my own wealth over sort of a long period of time.”
I have two thoughts on the GFL take private transaction. First, I am fine if it doesn’t happen. I don’t believe the market fully appreciates the Secure acquisition, and the combination of these two businesses is going to make the combined company a FCF compounding machine. This will be more evident once the Secure transaction closes, so I don’t think the GFL shareholders will have too long to wait for substantial price appreciation in GFL’s stock. Second, I do think the take private deal happens. GFL has never received the multiple it deserves in the public markets, and I think Patrick is frustrated by it. Also, Patrick can probably grow GFL a lot faster as a private company, and that notion appeals to him. The question is at what price does it go private? A number starting with a 4 would likely be rejected by the special committee and/or shareholders. $50 may get a deal done, but it would probably upset large public market institutions that the company would need if it ever went public again (a likely outcome for a PE investment). I am thinking $55 to $60 per share gets the deal done and makes everyone sufficiently happy.
Back to the Secure deal. One frustration that I have had in reading some equity research reports on the Secure Transaction is that some analysts assumed that the lack of a reverse break up fee makes Secure’s position weak and that GFL could walk by paying an expense reimbursement of $20MM. Well yes, the merger agreement does contemplate an expense reimbursement cap; however, that does not mean there would not be damages if GFL failed to close. Reverse breakup fees don’t make a merger agreement stronger; they just cap the damages. The Secure/ GFL merger agreement contemplates damages occurring if GFL fails to close and given the lack of a reverse breakup fee, the damages would be uncapped. This shouldn’t be an issue as Patrick directly addressed this by saying “I saw some notes….on whether you could try to pay a break fee and walk away from Secure or something. That is not – these buyers that have approached us – they love the Secure asset as much as they love the GFL business.” He also noted that “…two of these parties that approached us were doing a significant amount of work on Secure and believe Secure was an exceptional acquisition…” So, as it relates to the produced water / solid waste narrative, you have some of the smartest private equity investors in the world who now understand and support this narrative. This bodes well for the produced water players in the Permian Basin. It would not surprise me in the future if the Permian Basin produced water companies attract both interest from financial sponsors as well as strategic interest from municipal waste companies.
Overall, while I think GFL ultimately goes private, I am indifferent as investors should win either way. GFL should change their name from Green For Life to Get F’ng Long!
Texas Pacific Land Corporation
TPL had a strong quarter, with operating income up 33.4% YoY. This isn’t surprising given that now 59% of their revenue comes from oil and gas royalties, and oil and NGL prices were up significantly over the last year. Their produced water pore space business did well. It was up 20.6%, which is highly supportive of their stock price. Their water sales were down sequentially, but not that big of deal in my opinion. There were a few things from the call that jumped out to me.
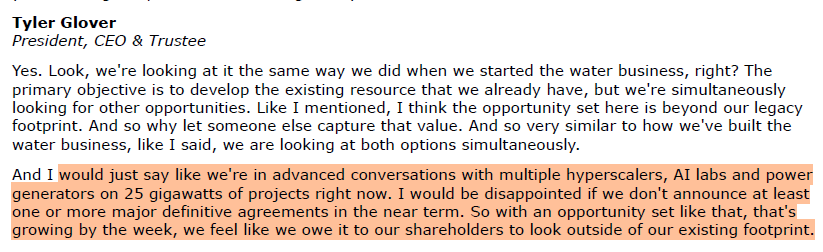
First, TPL CEO, Tyler Glover, stated that they are working 25GW of AI projects right now and he would be disappointed if there is not one or more major projects announced in the near term. While Tyler may talk down the price of TPL stock to the displeasure of many shareholders, one thing that he does not do is over promise and under deliver. The bullishness in his answer, which you can read below, is a marked change from previous conference calls and likely means they are very close to some announcements.
The next item that jumped out was the announcement of spending $110.2M to buy land in Shackelford and Jones Counties, TX. These two counties are not in the Permian Basin. It came up on the call that they have been working for a year on the project and that they are working on it with Bolt Data & Energy, the Eric Schmidt-founded company in which TPL made a significant investment.
Lastly, the negative reaction to the earnings release and the earnings call was curious. My take is that it is related to the out of basin land purchase. Many shareholders, particularly long-time shareholders, have been critical of management’s capital allocation practices. Specifically, the lack of share repurchases, and the amount of capital spent buying royalties, the latter increases the size of one of the lower quality business segments and is an area where management has a limited-to-no edge. Perhaps management is losing the trust of the broader market. That said, I think the market got this one wrong. It is comforting that this purchase was made in partnership with Bolt. One could imagine a scenario where Bolt approached TPL and said, “we don’t have a balance sheet, but you do. You buy the land and we will get a hyperscaler client”. I think that is what is happening in this case.
It probably behooves TPL to do the following. Add a board member with deep datacenter expertise (could be an investor in that space) and / or add a senior employee from the datacenter sector. At this point, it is clear that the Permian Basin datacenter thesis is playing out. It is also clear that TPL is hoping to monetize its land position from datacenters by being a supplier of water as opposed to leasing land. As this play develops, TPL will likely have to deploy an ample amount of capital to build the requisite infrastructure to supply water to datacenters. When the water business was first formed, there were calls to separate TPL into two businesses, a royalty company and an operating company. It would not surprise me if TPL revisited that idea.
WaterBridge Infrastructure
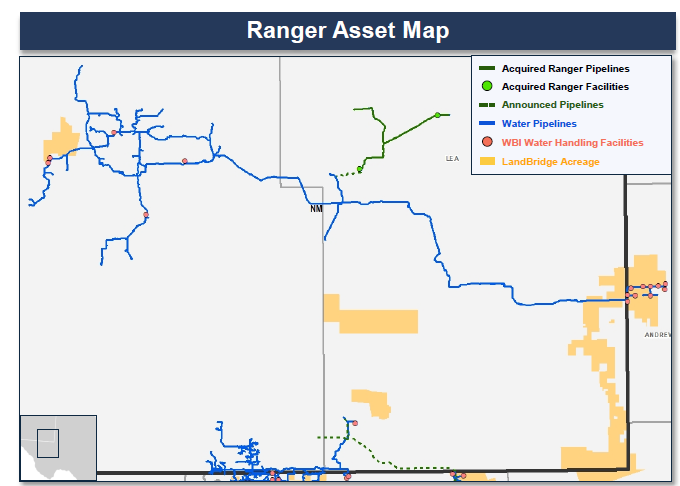
Aside from the strong financial results, revenue up 8.4% QoQ and 14.5% YoY with EBITDA up 12.5% and 23.7% the same periods, what stood out were WaterBridge’s investments and acquisitions. To start, WaterBridge acquired Ranger Water Midstream in Lea County. This brings with it 30 miles of pipelines, incremental pore space, and 1.2 MM barrels of water storage capacity. It also brings new customer relationships. This acquisition should help WaterBridge’s efforts in gathering water for the Speedway projects. Speaking of Speedway projects, Speedway 1 started flowing just after the close of the quarter, so the strong results excluded Speedway volumes, which are ramping up now. Speedway 2 FID could be announced “imminently”.
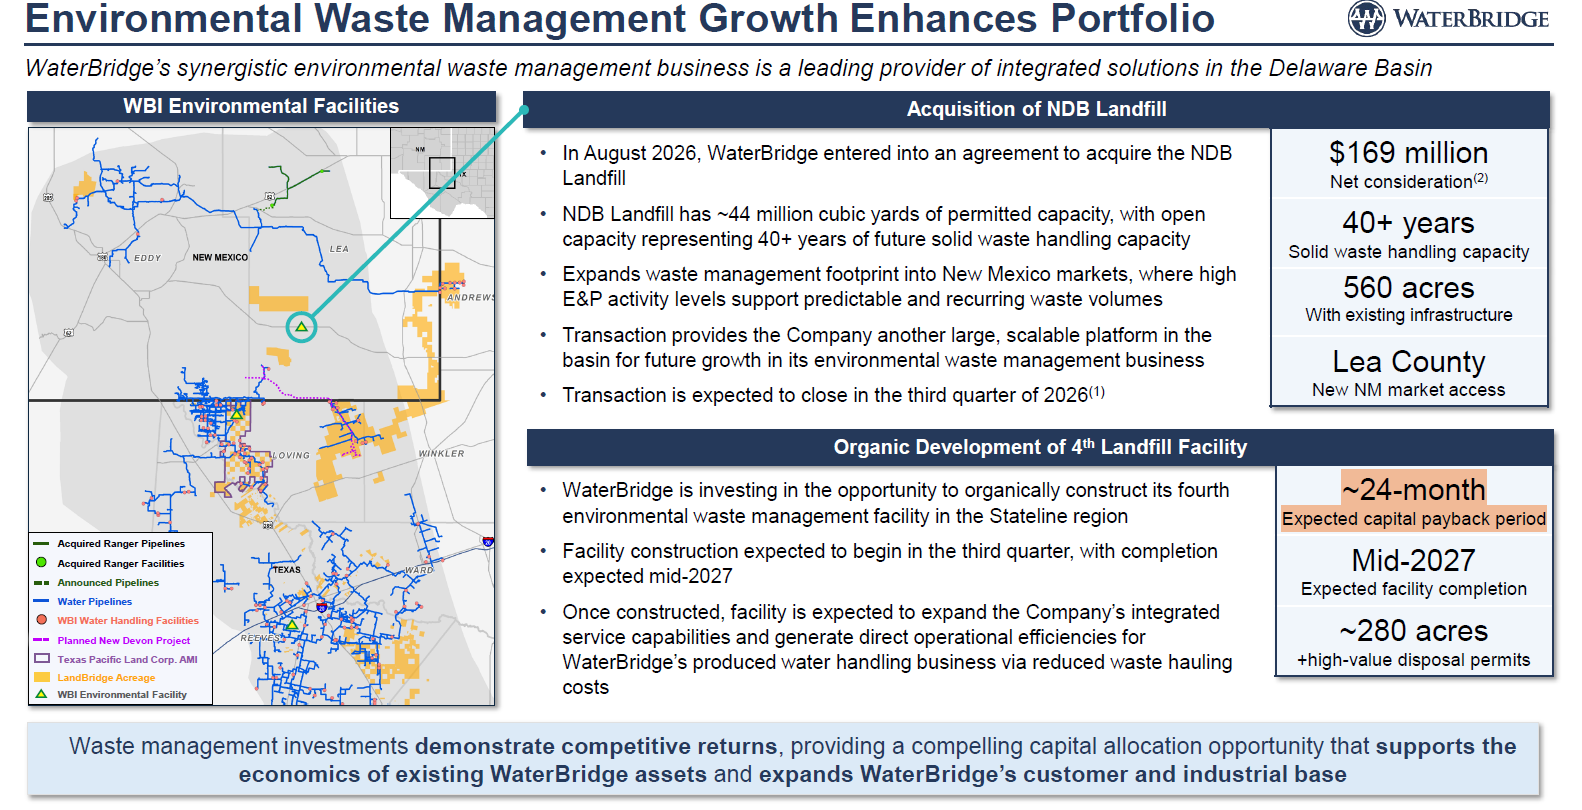
The next significant item was the acquisition of a landfill in Lea, County New Mexico and the investment in the construction of a separate landfill in the Stateline region. This doubles WaterBridge’s solid waste exposure from 5% at the time of the IPO to 10%. Aside from utilizing solid waste landfills for solids produced in produced water disposal, the expansion of solid waste exposure makes a lot of sense. Produced water disposal and solid waste have similar regulatory and geographic moats, often the same customers, and generate similar economic returns. The organic investment in the space is expected to have a 24-month payback period, which should yield a juicy IRR for a company that is over 3x levered.
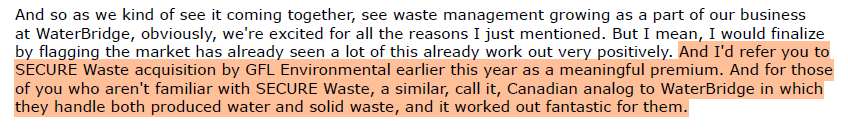
WaterBridge CFO Scott McNeely specifically called out the GFL / Secure Transaction as evidence of other players seeing the similarities between solid waste and produced water disposal. Sometimes I feel like I am the only one pounding drum (aside from the management of Secure that is, they do a good job beating the same drum) on solid waste and produced water similarities. However, after this quarter it is not just one crazy Substack writer talking about it. You have GFL acquiring Secure; and you have the largest sponsors in the world looking at buying GFL with Secure; and you have WaterBridge investing in solid waste. As the solid waste sector gets back into favor and returns to trading at high multiples (high-teens to low-twenties EBITDA), you should see WaterBridge follow suit.
The only negative item this quarter was the stock price reaction, which was silly. I think the negative reaction could have come from the modest guidance increase in light of the acquisitions, which I think is likely driven by management sandbagging as opposed to a weakness in the legacy business. The market could be sensing an equity raise. WaterBridge will be deploying an ample amount of capital in the form of acquisition consideration and growth capex by the end of this year, with additional growth projects coming next year. They could easily fund this year’s projects internally, but if management wanted to be conservative, they could bolster the balance sheet with some cash from a small raise. I would not view such a raise as an issue given the growth WaterBridge will be financing and the high returns that growth it will generate. One easy change for WaterBridge to make that may also help the stock price would be to breakout growth and maintenance capex in their financials.
LandBridge
LandBridge crushed it this quarter with revenue going up 31% QoQ. This was driven by a 41% QoQ growth in revenue from surface use easements (mostly produced water easements). This growth should continue to ramp up the balance of the year as volumes from Speedway 1 hit it. The big news from this quarter was the announcement of being in late-stage negotiations with seven counter-parties for datacenter/power gen facilities representing more than 10GW. Additionally, the company will soon convert to a C-Corp, which is the first step in gaining index inclusion. I have long discussed that LandBridge is an attractive investment on the pore space alone (2) and that the datacenter opportunity was a free call option. I still believe that the company is attractive just on its pore space opportunity, but the datacenter call option is now starting to look in the money.
It is worth a quick mention that LandBridge participated with WaterBridge in the landfill acquisition. They essentially paid high single digits EBITDA for a royalty stream that should grow over time. This should help LandBridge’s stock price from bootstrapping alone.
EagleRock – Welcome to the Party Pal
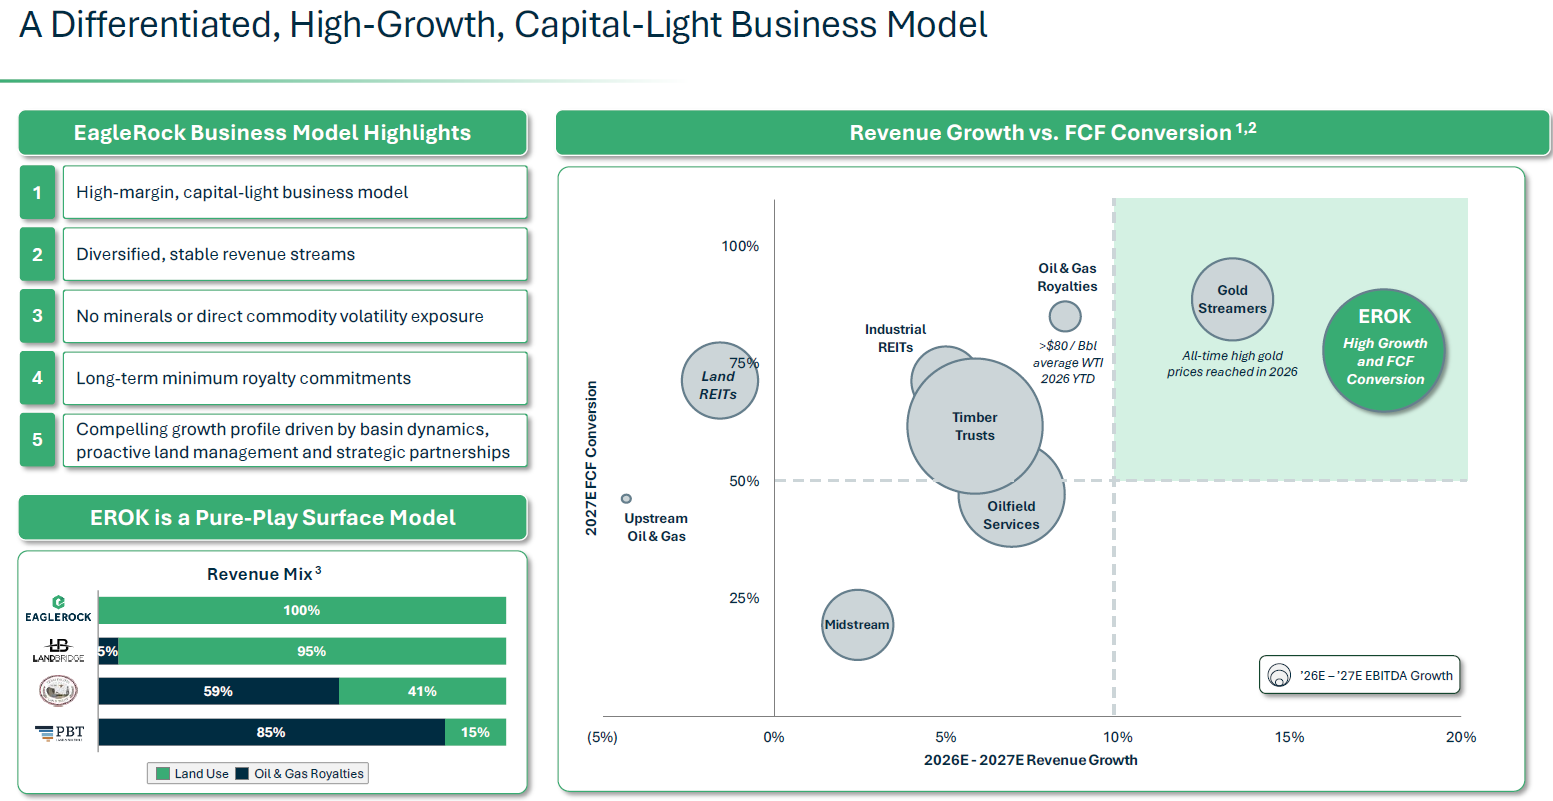
EagleRock completed their IPO in May and hosted their first earnings call. They had a good start by delivering 34% sequential growth in revenue and 29% sequential growth in EBITDA. What jumped out was their focus on reminding the market that they do not have any mineral royalty revenue. Their revenue comes from surface use royalties, surface use revenue, and resource sales, which are much more durable and recurring than mineral royalties. This is a point I agree with and often make (3).
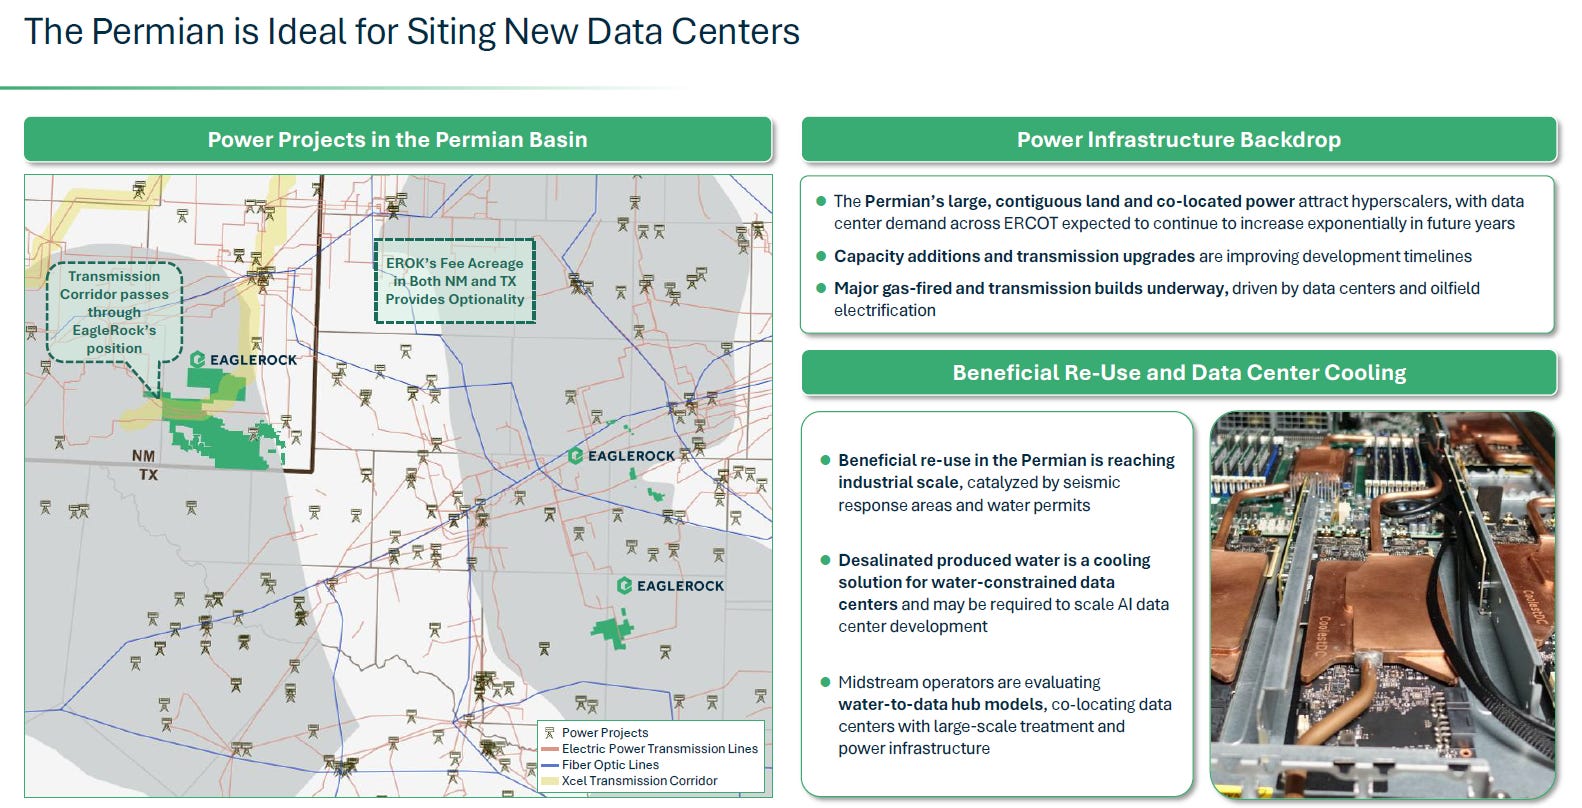
The next item that jumps out is the talk of using water for data center cooling, which came up in TPL’s, LB’s, and WBI’s presentations as well. There are a lot of companies trying to get datacenters off the ground in the Permian, but the ones who should be successful in the long run have ample land (in the right locations), brackish water availability, and produced water origination and transportation capabilities.
This was certainly an interesting quarter with a lot of big announcements. Something tells me we will have several interesting announcements before the third quarter conference calls.
Index:
https://310value.substack.com/p/first-takes-on-gfls-acquisition-of
https://310value.substack.com/p/water-and-power-the-dual-engines
https://310value.substack.com/p/two-companies-marked-safe-from-the
Disclaimer: For educational and entertainment purposes only. Not a solicitation or and offer to buy or sell any security. Do your own due diligence. Author is long several of the companies and is under no obligation to update position changes.